The Fed Lost the Wheel
Why three of Goldman’s top traders just said the Fed no longer controls interest rates, what really grabbed the wheel, and why the smart money is quietly buying gold
Felix Nikolas Prehn · 10 September 2026 · 13 pages
Bottom line
In a single week, two desks at the same Wall Street bank said the quiet part out loud. One said the Federal Reserve is now “much more passenger than driver” — that a trillion-dollar wave of AI borrowing, not the Fed, is setting the interest rate on your mortgage and your savings. The other told clients to keep buying gold on the dips. Same bank. Same week. This report explains why those two messages are really one story — and why it lands on your money.
$1.3Tnext year’s planned AI build-out — a borrowing wave on track to be bigger than the US Treasury itself
Bottom Line
The Fed lost the wheel
Move 1
The Fed became a passenger. Three of Goldman Sachs’ most senior traders said on camera that “the Fed are much more passenger than driver.” The one institution whose entire job is to steer the price of money is, according to the people who trade the bond market every day, no longer the one driving.
Move 2
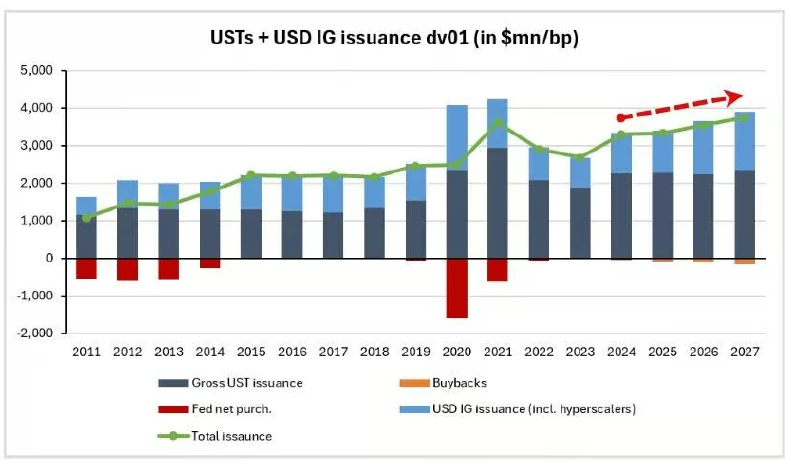
A borrowing wave grabbed the wheel. To build AI, the big technology companies are borrowing on a scale that is hard to picture — roughly 500 billion dollars of AI-related debt already this year, and around 1.3 trillion penciled in for next year. That wave, not the Fed, is now setting the long-term interest rate.
The combination
Higher rates, warmer inflation. When a handful of firms floods the bond market and out-borrows the US Treasury, the interest rate that matters — your mortgage, your car loan — gets pushed up and stays up, whatever the Fed announces.
The tell
Follow the money, not the mood. In the same week, Goldman’s metals desk told clients the recent gold dip is “an elongated pause” and to keep buying — because the central banks of the world are quietly cornering the supply.
The Fed Is Just A Passenger
“Much more passenger than driver”
Who said it
Not junior analysts. The panel was Mark Wilson (head of equities franchise sales), Jan Scheffel (global co-head of short-term macro trading) and George Cole (head of European rates strategy) — the people who move the actual bond market, not commentators.
What they said
AI is now a bond-market story. Their message was blunt: AI has stopped being just a stock-market story and become a rates-and-credit story. Wilson called it “the most capital-hungry investment cycle in history.”
Why the Fed can’t steer
It only sets one rate. The Fed sets the very short-term, overnight rate. But the rate that matters for your mortgage and the whole economy is the long-term rate — and that is set by a giant tug-of-war in the bond market the Fed did not create and cannot switch off.
The plain-English version
It can tap the brakes, not the gas. That is what “passenger” means. The Fed can nudge, but the foot on the accelerator belongs to the AI build-out now.
The Trillion-Dollar Borrowing Wave
About to out-borrow the US Treasury
The size of it
Half a trillion, already. By early August, AI-related debt had climbed toward 500 billion dollars — about one-fifth of all high-grade corporate borrowing in America this year. One theme, one-fifth of the whole thing.
And that’s the warm-up
1.3 trillion next year. Nobody has yet figured out how to fund next year’s build-out, penciled in around 1.3 trillion dollars. Next year, this handful of tech firms is on track to issue more interest-rate risk into the bond market than the United States Treasury.
Why it moves your rate
The savings pot is finite. Goldman’s traders said the “savings-glut” era is over — AI firms, governments, defense and reshoring are all bidding for the same limited pool of savings at once.
The mechanism
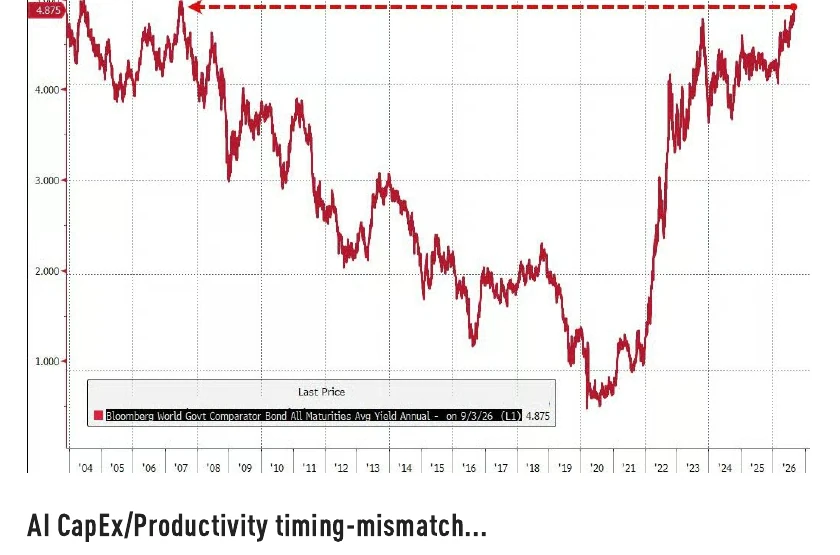
New bonds crowd out the old. When tech floods the market with new bonds, investors sell what they already own — Treasuries — to buy them. Selling Treasuries pushes their yield up. That yield is the anchor for your mortgage, your car loan and the interest on the national debt.
Why This Reaches Your Bank Account
Higher rates, warmer inflation
- AI floods the market with new bonds
- Investors sell Treasuries to buy them
- Long-term interest rates get pushed up
- Your mortgage, loans and inflation feel it
The inflation twist
“Implicitly inflationary.” Jan Scheffel’s phrase. The economy is paying for AI’s payoff — the cheaper, faster future — before that payoff has shown up. All the spending now, the productivity later. That gap quietly lifts the underlying interest rate for the whole system.
Not just America
The West and Japan too. The same fiscal strain — enormous deficits, a huge interest bill on the national debt — is showing up across the developed world. When governments owe more than they can comfortably pay, every exit they have quietly cheapens their currency.
Can’t the Treasury fix it?
A firecracker in a hurricane. One veteran trader described Treasury bond buybacks against this tidal wave of AI debt as symbolic — good messaging, nowhere near big enough to matter against 500 billion this year and 1.3 trillion coming.
The honest part
This is slow, not a crash. Nobody is saying rates spike overnight. The risk is quieter: your cash slowly buys less while the world moves some of its savings into things that cannot be printed.
What The Smart Money Is Doing
The vaults are cornering the gold
- 3,500t
- total new gold mined in the world each year
- ~1,100t
- bought by central banks each year now — up from 400–500t before 2022
- ~1/3
- share of all new gold the vaults now swallow — and never sell
The one number that matters
A third of all new gold, gone. The world mines about 3,500 tons a year. Central banks used to take 400–500 tons of it; today they take closer to 1,000–1,100 tons — roughly a third — and they bury it in a vault and leave it there.
Why it matters so much
The funnel got narrow. With the vaults quietly swallowing a third of supply, the pile left for everyone else — jewelry, coins, funds, you — is dramatically thinner. As Goldman’s Tony Kim put it: “You don’t need as much investment capital to drive prices materially higher.”
Why they’re doing it
The lesson of 2022. When Russia’s central-bank reserves were frozen, every other country had the same private thought: that could be me. So they moved national savings out of paper they could be locked out of, into gold in their own vaults. Kim calls it a regime change.
Behaviour beats opinion
You can see what they buy. You don’t have to guess what the biggest, most patient money thinks. It is buying the one form of money no government can print — every single year.
The Gold And Silver Forecasts
“$4,000 is a pretty solid floor”
The gold call
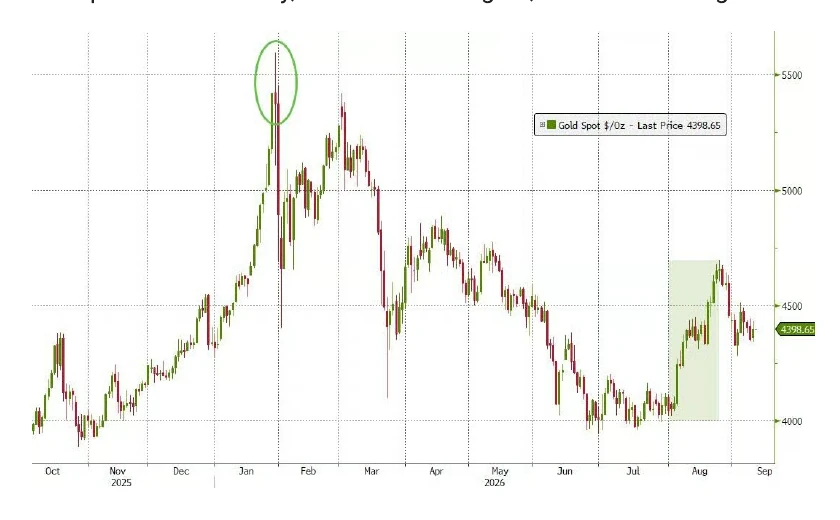
Not the top — a pause. Tony Kim, Goldman’s global head of metals trading, said the recent drop “isn’t the end of the bull market, it’s an elongated pause,” and that “new highs are going to be in the future.” On price, he called 4,000 dollars “a pretty solid floor” and told clients to scale in on the dips into the Fed’s next meeting.
The rates twist
The old see-saw can break. Normally gold falls when rates rise. But when rates are rising because people are scared about government finances, they buy gold at the same time. Kim’s tell: “Any time you see official policy intervention, people tend to buy gold.”
The silver warning
Bigger upside, bigger stomach. Silver is a much smaller market — about half of demand is industrial, and only ~20% is true investment demand, which is what sets the price. Kim floated 50, 80, even 100 dollars if buyers pile in together — but warned of 20–30% air pockets, “spot up, vol up.” Central banks buy gold, not silver, so silver has no steady floor beneath it.
The trade, in his words
“We’re still bullish gold.” The nearest catalyst he is watching is the inflation report this Friday, heading into the Fed meeting.
Why Cash Is The Guaranteed Loser
When rates stay high, cash still leaks
The setup
A Fed that can’t hold rates down. If the long-term rate is now being set by an unstoppable wall of AI borrowing, and that borrowing is — Goldman’s own word — inflationary, then holding cash becomes a slow, guaranteed leak. Your money sits still while prices climb.
Bonds aren’t the old safe haven
The flood moves their value. Government bonds used to be the automatic safe place. But the very wave of new debt is what keeps pushing their price around — the safety is not what it was.
Why gold holds up
You cannot print it. Gold’s whole appeal is that its supply grows slowly and no government controls it. When confidence in paper money is under pressure, that scarcity is exactly what people want — which is why the vaults are buying.
The takeaway
“Do nothing” is a decision. Sitting entirely in cash feels safe, but over long stretches it has been a guaranteed slow loss of buying power. That is the trade-off to understand before you leave everything where it is.
What This Means For You
A plan matters most when the headlines feel loud
The bubble on top of it all
The AI build-out is also a bubble risk. The same borrowing wave driving rates is funding the biggest speculative build-out since the year 2000. If the AI payoff shows up later or smaller than promised, the fall would not be gentle.
The history that should worry you
The internet was real, and it still crashed. The internet was arguably the greatest invention of our lifetime — and the Nasdaq still fell 78% after 2000, and took 15 years to climb back. The technology being real does not stop the bubble from bursting.
Make it personal
Picture a 55-year-old with $100,000. That is roughly the average retirement pot in your 50s. A 78% drop, like the Nasdaq’s, turns 100,000 dollars into about 22,000 — and history says it might not recover until you’re 70. This already happened to millions of people once.
See your real exposure
Look through your index fund. Most people think their index fund is safe and diversified. But a handful of giant tech names — the very ones borrowing to build AI — now make up a huge chunk of it. In the Winston app you can pull up any fund and see straight through it to how concentrated you really are. The real fix is a simple, calm plan for your 401k, pension and retirement — so a crash is something you prepared for, not something that happens to you.
Questions for the reader
Five questions to ask before the next headline
- Do I have 3 to 6 months of expenses set aside without having to sell investments?
- How much of my long-term savings is sitting in cash that quietly loses value in a higher-for-longer rate world?
- Do I own anything that a government cannot print — like gold or silver?
- Am I overexposed to the exact big-tech AI names driving the borrowing wave, without realising it?
- If the market fell 50–78% like it did after 2000, do I have a plan — or would I panic?
Disclaimer
This report is for educational and informational purposes only and does not constitute financial, investment, legal, tax or accounting advice. It is not a recommendation, solicitation or offer to buy or sell any security, currency, commodity or financial product. No buy/sell rating or price target is provided. All investments involve risk, including the possible loss of principal. Forecasts and price targets described here are the published views of third parties, may be wrong, and may not repeat. Historical comparisons are illustrative and simplify complex events. Readers should do their own research and consult appropriately qualified professionals before making financial decisions. Past performance is not indicative of future results. The Prehn Institute makes no guarantee regarding outcomes.
Author: Felix Nikolas Prehn, The Prehn Institute.
Companion essay
This briefing sets out the evidence and sources. Felix Nikolas Prehn's personal interpretation of the same subject is published as an essay on felixprehn.com: AI borrowing has displaced the Fed, and every asset price follows from that single shift