The Unthinkable and the Dollar
Why raising rates into an oil shock echoes the 1970s — and why the smartest money is quietly moving into gold and silver
Felix Nikolas Prehn · 25 September 2026 · 19 pages
Bottom line
The Federal Reserve has started raising rates into an energy shock, the same combination that produced stagflation in the 1970s. With debt-to-GDP back near 120%, the authorities cannot hold rates high enough to kill inflation, so the likely path is to let inflation quietly erode the debt — and the value of cash savings along with it. This report explains the mechanism and what history says tends to protect purchasing power.
8×how far gold rose (roughly $100 to $850) the last time a central bank raised rates into an oil shock
Bottom Line
The 1970s setup, again
Bottom line. A rate hike into an oil shock does not cool the cause of the inflation — energy costs — it only squeezes borrowers and slows the economy. History calls the result stagflation, and last time it sent gold up roughly eight-fold. The same ingredients are lining up now.
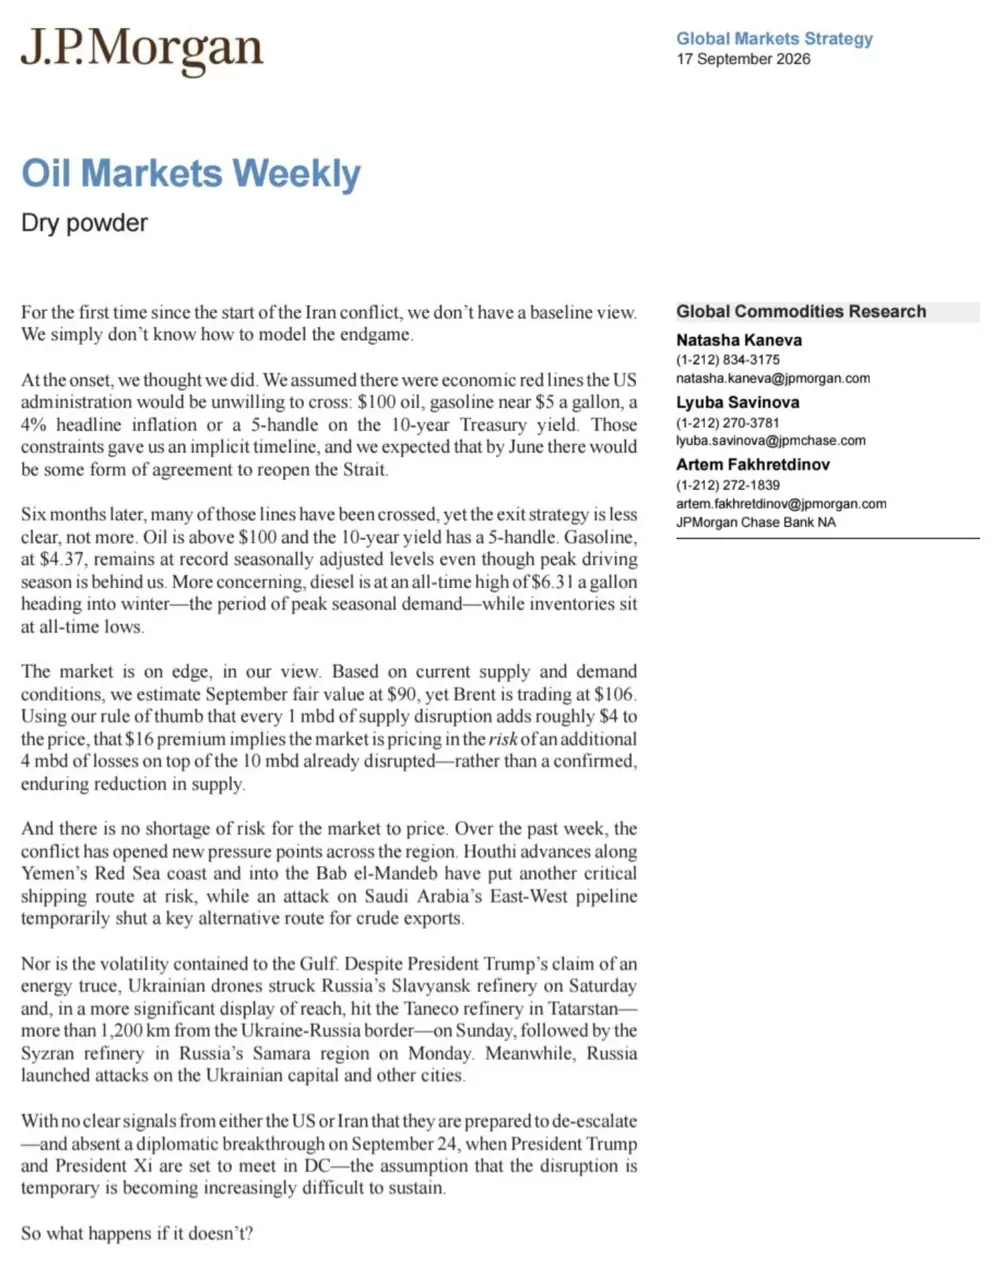
- Oil back above $100
- Fed raises rates into it
- Growth slows, prices stay high
The trigger
An energy shock, not a demand boom. Prices are rising because the stuff underneath everything — fuel, fertiliser, freight — got more expensive. Raising rates does not touch that cause.
The trap
The debt is too big to fight inflation properly. At roughly 120% debt-to-GDP, holding rates high enough for long enough would blow up the government's own budget first.
The likely path
Inflate the debt away. Letting inflation run quietly shrinks the real size of the debt — and the real value of savings held in cash.
The response
Follow the smartest money. Central banks now hold more gold, as a share of reserves, than at any point this century. The report explains why that matters to a regular saver.
The 1970s Mistake
Not all rate hikes are the same
| Situation | Why prices are rising | What a rate hike does | Result |
|---|---|---|---|
| Hiking into a boom | Too much demand chasing too few goods | Cools demand at the source | Prices settle — the tool fits the problem |
| Hiking into an oil shock | Energy costs push up the price of nearly everything | Punishes borrowers; leaves energy costs untouched | Growth falls, inflation lingers — stagflation |
Why the difference matters
The medicine has to match the disease. When demand is the problem, higher rates help. When energy is the problem, higher rates hit the wrong target — the family with a mortgage, the small business with a loan, the farmer financing next season.
The historical echo
The 1970s are the template. Oil shock, roaring prices, a central bank tightening into a weakening economy. The textbooks had said stagnation and inflation could not happen together. They did, and gold rose from around $100 to about $850.
The tell
Ask which kind of hike this is. When someone says “rates up, gold down,” the important question is whether the hike is into a boom or into a shock. This one is into a shock.
On the Ground
$1,000 to fill one combine
- $7
- per gallon of diesel described by the farmer in the source material
- 140
- gallons in the combine's tank
- $1,000
- to fill it up once
Bottom line. An energy shock is a tax on the whole economy. Whatever it costs to grow and move food, the consumer pays at the other end. This is cost-driven inflation, and it is exactly the kind a rate hike cannot fix.
The voice from the field
A veteran American farmer. The source material quotes John Boyd Jr describing diesel at $7 a gallon, with fertiliser, chemicals and equipment all climbing at once, and calling it one of the worst economic times in history for America's farmers.
Why it spreads
Energy sits underneath everything. Higher diesel raises the cost of the tractor, the fertiliser, the lorry and the packaging. Each hand it passes through adds its own higher costs, so the original spike is multiplied several times before it reaches the shelf.
The point
This is not overspending. It is a producer being crushed by input costs he cannot control — the signature of supply-side inflation.
Why the Tool Misses
Why supply-side inflation is so stubborn
- Energy costs push prices up across the board
- Higher rates raise the cost of borrowing
- Families and firms cut back and slow the economy
- But energy is still expensive — so prices stay high
The disease vs the medicine
Rates treat demand; this is a supply problem. When the price of everything is being dragged up by energy, a higher borrowing cost does not make the oil or fertiliser any cheaper. It just weakens the borrower on the other side.
The feedback loop
Costs cascade. The farmer charges more for grain; the haulier charges more for freight; the shop charges more for the loaf. An energy shock does not stay in the energy aisle — it ends up in every aisle.
The one-sentence trap
The medicine does not treat the disease. It just weakens the patient — you kill the growth, not the inflation.
Already Happened
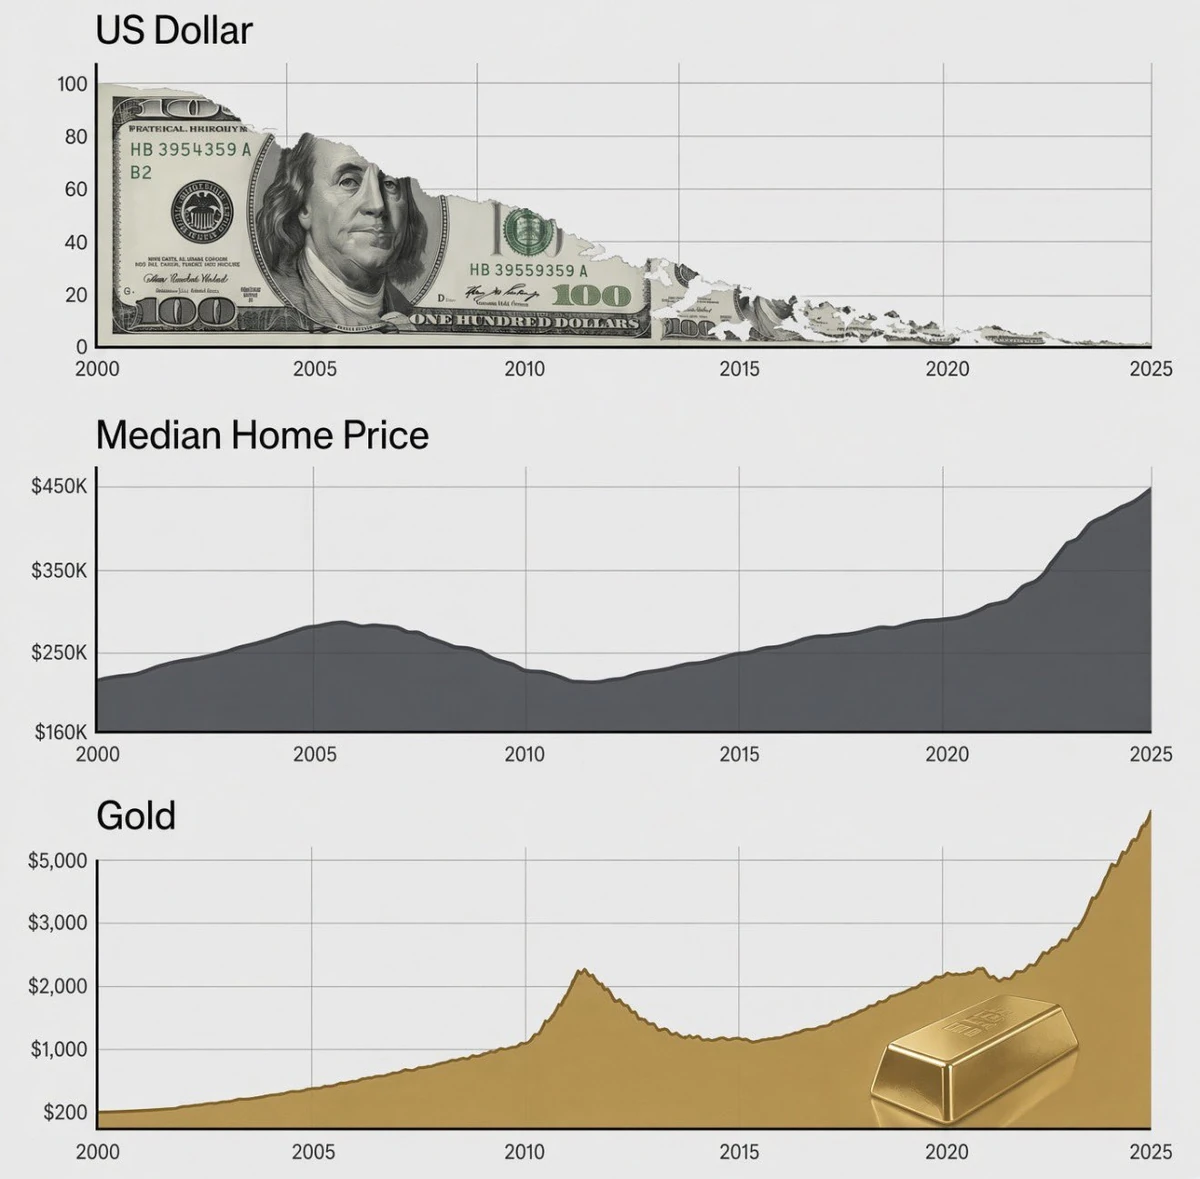
25 years of holding wealth in cash
Why They're Trapped
Raising the price of their own mortgage
How the government borrows
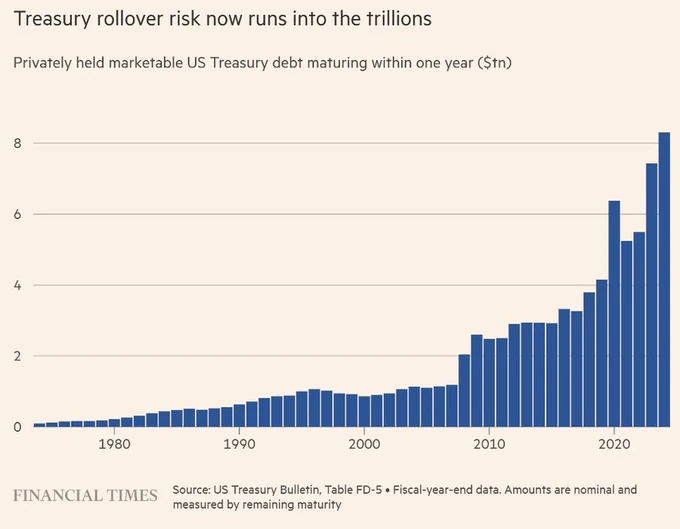
Treasuries are just IOUs. You lend the government money now; it repays later with interest. The problem is the sheer size of what must be repaid and rolled over.
The rollover
Roughly $8 trillion in 12 months. The source material notes about $8T of government IOUs coming due within a year and needing to be borrowed again — at today's rates, not yesterday's.
The catch
Every rate rise is self-inflicted. Higher rates make the government's own debt more expensive to carry. They are raising the price of their own mortgage.
Volcker Could. They Can't.
Why today is not the early 1980s
- ~3.3%
- average rate on the old debt
- ~5%
- rate on rolling it today
- ~$136B
- extra annual interest from rolling $8T at today's rates
| Measure | Volcker era (early 1980s) | Today |
|---|---|---|
| Debt-to-GDP going in | Driven down to roughly 30% | Back at roughly 120% |
| Room to raise rates hard | Yes — the country barely owed anything relative to income | No — punishing rates would blow up the budget |
| Annual deficit backdrop | Smaller relative to the debt | Roughly $2 trillion a year more spent than taken in |
Inflate, Then Hike
First you inflate the debt away
- Let inflation run a little hot
- The real size of the debt shrinks
- Only later raise rates to finish the job
Bottom line. When a government owes too much and inflation is running, the old playbook is to inflate first and hike later. We are firmly in the inflate-it-away part. The person who pays for that is whoever holds dollars.
How it works
Debt is repaid in cheaper money. If a government owes a trillion and inflation runs at 5–6% for a few years, the debt on paper stays a trillion, but what a trillion can buy shrinks. The debt gets easier to carry — not because it was paid down, but because the money weakened.
Who pays
The saver. Every bit of relief the government gets is lifted from the pocket of whoever saved in the same shrinking dollars. Nobody votes for it, nobody announces it — which is exactly why it is used.
The theatre
Watch what they can afford, not what they say. A small hike lets them look tough while the arithmetic of the debt means they cannot follow through.
The Auctions
A wall of debt to sell every week
- $457B
- Treasuries auctioned in a single four-day stretch, per the source material
- $171B
- on Monday alone
- Weekly
- this has to be repeated, week after week
The mechanism
Not enough buyers means higher rates. If demand is weak, the government must offer a higher interest rate to tempt lenders in. Higher rates to sell the debt mean more expensive borrowing everywhere and tighter conditions.
The squeeze on your investments
Money gets pulled from shares into bonds. When Uncle Sam pays a fat rate on his paper, capital leaves the stock market to sit in bonds — a tug of war that can knock the wind out of shares while the value of the cash itself keeps eroding.
Oil, and the Buyer of Last Resort
The printing press waiting behind the wall
- Not enough buyers at a price the government can afford
- The central bank steps in and buys the debt
- New dollars are printed to soak it up
- Every new dollar waters down the ones in your pocket
Follow the Institutions
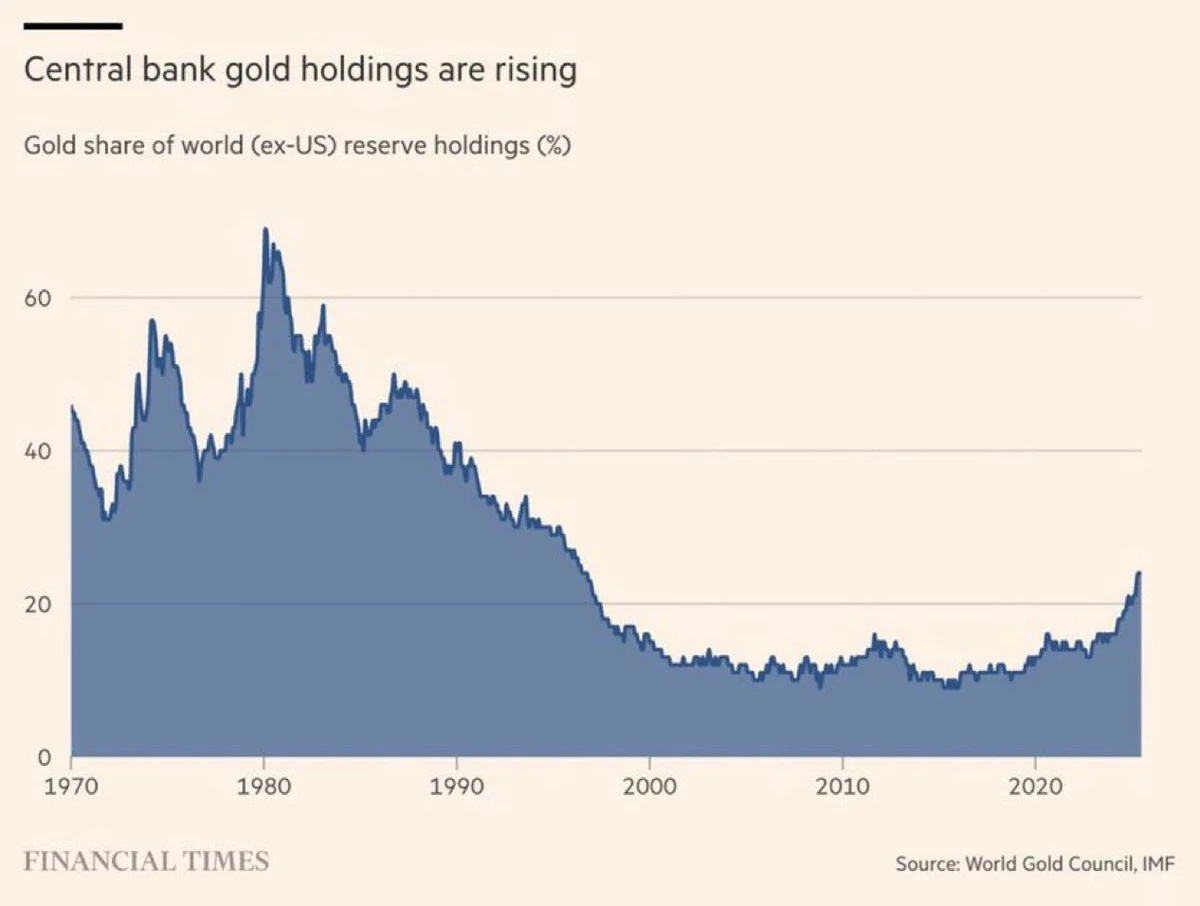
The most gold this century
Who is buying
The people who print the money. Central banks now hold more gold, as a share of reserves, than at any point this century. They are choosing to hold less of their own product and more of the one thing they cannot print.
What it signals
A vote of no confidence in paper. Read alongside the melting-dollar chart, the message is consistent: the institutions closest to the printing press would rather not be on the losing side of it.
Watching it yourself
A personal newspaper for your money. The Winston app tracks gold, silver, the dollar and whatever you hold, in plain English. You do not need any app to get the point — but it helps you notice before the headline, not after.
The Comfortable Mistake
“I'll just sit in cash”
Bottom line. Cash feels like the one thing that can't go wrong. Over time it is the asset designed to lose. Since 1971, when the dollar's last link to gold was cut, it has lost the overwhelming majority of what it could buy.
The long erosion
1971 was the turning point. Before it, a dollar was a claim on something real. After it, the supply could grow without limit — and it did. The government's own inflation calculator still shows a dollar from back then worth a small handful of cents today.
It doesn't bleed slowly
Calm, then a spike. You get years of quiet and then a sharp jump — as many people saw after the pandemic, when a hotel room that cost a couple of hundred suddenly had a zero bolted on. That was the money getting worse, not the room getting better.
The setup now
The next spike is being loaded. With an oil shock feeding into everything and a printing press on standby, the conditions for another jump are in place.
What People Work Out Early
Things that can't be printed
| Asset | Character | Why it's mentioned |
|---|---|---|
| Gold | The steady one | The asset central banks are actively stacking |
| Silver | The smaller, wilder cousin | A tiny market that can sit still for years, then move late and hard |
The silver mechanism
A small door, a lot of money. The silver market is tiny next to gold. When big money gets nervous about the dollar and spills into silver as the cheaper way to make the same bet, there isn't enough to go round — so the price can lurch rather than drift. This is a description of the mechanism, not a promise it will happen.
The real point
Diversification, not all-in. This is not advice to buy anything, and a portfolio that is all gold and silver would rob you of sleep. The point is to know what you actually own.
The hidden concentration
Many savers are less spread out than they think. If a large share of recent gains came from a small clutch of AI shares — as it did for many index-fund holders — that is concentration in the most crowded corner, not protection.
The Whole Picture
One machine, in one place
- Rates raised into an oil shock — the 1970s mistake
- Debt too big to hold rates high enough to kill inflation
- Inflation left to melt the debt — paid for by savers
- Central banks hold the most gold this century
What to hold onto
Understanding first. You do not need to predict the exact month of the next spike. You need to understand the machine well enough to stop holding all your wealth in the one asset designed to lose.
Don't panic
This is not a sell-everything message. Don't panic-sell your shares. Know what you own, and make sure you are actually diversified against the risk described here.
Questions for the reader
Five questions before the next spike
- Do I know what share of my wealth is sitting in cash and cash-like savings that inflation can quietly erode?
- Am I genuinely diversified, or concentrated in a small clutch of crowded AI and tech names?
- Do I own anything that tends to hold value when confidence in paper money is under pressure?
- Do I understand why central banks are buying gold — and whether that logic applies to me?
- Do I have an actual plan for a sustained bout of inflation, or just a hope that it sorts itself out?
Disclaimer
This report is for educational and informational purposes only and does not constitute financial, investment, legal, tax or accounting advice. It is not a recommendation, solicitation or offer to buy or sell any security, currency, commodity or financial product. No buy/sell rating or price target is provided. All investments involve risk, including the possible loss of principal. Market events, relationships and historical comparisons described here may not repeat, and figures cited are drawn from the video's source materials rather than refreshed with independent research. Illustrations simplify complex systems and may omit factors. Readers should conduct their own research and consult appropriately qualified professionals before making financial decisions. Past performance is not indicative of future results. The Prehn Institute makes no guarantee regarding outcomes.
Author: Felix Nikolas Prehn, The Prehn Institute.
Companion essay
This briefing sets out the evidence and sources. Felix Nikolas Prehn's personal interpretation of the same subject is published as an essay on felixprehn.com: Raising Rates Into an Oil Shock: The 1970s Mistake Repeated